Monday, September 26, 2011

Where are the French?

...they must have all the love they need at home...
Mike Smitka
First it was the Japanese. Then a couple Germans and the Koreans. Now the rest of the Germans. The Italians have one foot in the water. But except for a fleeting presence through American Motors, both with Simca as a subsidiary and later with Renault as an owner, the French -- who dominated the global industry in its formative years in the 19th century -- are nowhere to be found. Why?
Now it may be that Renault's control of Nissan represents de facto entry. Certainly purchasing is handled on a global basis, and there's cooperation in engineering. It may be that some Nissan products currently on sale in fact use a Renault platform (Perhaps one of my readers can fill in the gap.) But the absence is puzzling.
That's even more true of PSA (Peugeot-Citroen). The last time I looked (I'm probably showing my years!) they were doing well in Europe and solidly profitable. They keep up with technology, as seen in the customer base of the winners of the PACE Supplier of the Year innovation award for which I'm a judge. They're simply not here.
So what is their strategy? Do they believe that sufficient technology resides in the supplier base that they do not need sheer size to fund the R&D for tomorrow's products? Are they making enough money in small cars that they've chosen to "stick to their knitting" -- not venture into segments with which they have no experience -- and are therefore passing up the US market with its cheap gas and penchange for fuel guzzlers?
I don't know, but I've started to think about the variance in such "macro" strategy across the top vehicle assemblers. Suzuki strikes me as the closest analog, but they have a strong base in India, though it's probably no longer accurate to say that they dominate the market through their joint venture Maruti. Then there's Daihatsu, but they were gobbled up by Toyota and so, for better or for worse, are shackled to the small vehicle niche. Daihatsu long ago exited the US market; Suzuki seems likely to. So maybe PSA made a sensible strategic decision, and refused to join the herd in entering (and now exiting) the US.
My curiosity is piqued, but I have no answers.

Wednesday, September 14, 2011

Can an Automaker Incentive Battle Goose the Economy?

David Ruggles
As the economy wallows in the doldrums, is there any cause for optimism? The outcome of the European debt crisis is still unknown, and we know how markets despise uncertainty. There are still plenty of uncertainties associated with the so called “Arab Spring” uprisings in the Middle East, and those could be with us for a while. While fuel prices have somewhat moderated, they remain high. The country’s credit rating took an unnecessary hit, although plenty of money seems to still be seeking to buy our debt. When the Dow fell dramatically after the downgrade of our credit rating, much of the money that left equities found its way into our “downgraded” Treasury bonds. Either the European debt crisis or our government being hamstrung by ideologues has sent the Dow on a downer after the debt ceiling crisis “semi resolution.” The 12-member “Super Congress” still has an important job to do, and there is additional uncertainty attached to that, that will take weeks to resolve.
The economic recovery that seemed so promising 10 months ago has stalled. Real estate prices continue to drop in many markets with many foreclosed properties not even listed to lessen the perception of burgeoning inventories of distressed merchandise. In Las Vegas a realtor friend mentioned that 50% of her deals these days are cash, as many properties don’t qualify for a certificate of occupancy and can’t meet standards for a mortgage. Only 20% of real estate market sales are “conventional sales,” she says. To put this in perspective, previous Federal Reserve Chairman Alan Greenspan says we shouldn’t expect any kind of robust recovery until home values rise at least 10%. His comment was made in an interview before values retreated another 5%.
Unemployment has plateaued at about 9%, with under-employment and fear of unemployment stifling consumers’ will and ability to buy. The President’s new jobs plan has been met with a collective yawn by Congressional Republicans. It is yet to be determined if can even pass, let alone actually make an impact if passed. The first stimulus package of the Administration managed to stem job loss of 780,000 per month, but did not achieve its stated goal of keeping unemployment below 8%. Despite stemming the job loss, the word “failure” is bandied about in political circles. As it turns out, the initial calculations of how much stimulus might be needed were based on preliminary numbers, which showed the economy contracted 3.8% in the last quarter of 2008. Once all the numbers were in, the real numbers showed a 6.2% retraction in that quarter. It turns out that to do the job promised, Paul Krugman, Nobel Prize-winning economist and New York Times columnist was correct, the stimulus needed to have been twice as large. Regardless, we are where we are, the original stimulus has exhausted its funds, the economy is stagnant, domestic auto stocks have tanked, and recovery has been stopped in its tracks.
This economic downturn isn’t like our previous ones. This one was caused by a financial crisis, with a near-collapse of the financial system averted at the last minute by government intervention. In my own business career, I recall the auto business being a major player in dragging the country out of economic stagnation. In late 1971, Pres. Richard Nixon repealed the excise tax on automobiles, touching off a spurt of business that pulled the economy out of stagnation and carried us forward to the first 10 million unit sales year in 1973. That momentum was halted in late 1973 by the OPEC oil embargo, fuel price spikes, and the associated economic downturn. Chrysler and Joe Garagiola helped pull us out of that one in 1975 with the “Buy a Car, Get a Check” promo. We then went through the Iranian hostage crisis in 1979, another spike in fuel prices, inflation, and the recession associated with the Carter/Reagan era and the first Chrysler bailout. Chrysler’s resurgence helped lead the economy out of the depths. In the past 10 years, GM led the industry and the economy out of the doldrums caused by the Sept. 11 attack with “Keep America Rolling” and 0% interest. That was followed by the “Employee Purchase Plan.”
This time around, we experienced the recession, the near insolvency of the banking system, a real estate crisis of epic proportions, and one that stubbornly hangs on, the temporary disappearance of financing of all kinds, bankruptcies of two of the three domestic automakers, and unthinkable job loss. After the restructuring of the auto industry, and a less than perfect “Cash for Clunkers” program, and a brief period of revival, any forward momentum has stalled.
Currently, new vehicle inventories are low. This isn’t a particularly abnormal situation for this time of year, as it is typical for dealers to clear out previous year’s stock to make room for the new model year’s models. But Japanese manufacturers, in particular, have lost ground against their competition because of the supply interruption caused by the tragic Japanese earthquake and tsunami. And they want their marketshare back. According to Kelly Blue Book, Japanese brands were approaching 40% of the U.S. market. Bus since April, that share has fallen to about 30%. Most SAAR projections are running behind pace, including my own. People are talking about an incentive battle from now through the end of the year. As Japanese brands gear up, domestics are expected to respond. And the domestics now have a much lower breakeven point than before their restructuring.
Incentive wars usually drive down used-vehicle values. But we have been experiencing an acute pre-owned inventory shortage. Dealers would welcome some relief.
Rental fleet replenishment is still in long-cycle mode. Wouldn’t it be nice to rent a vehicle again with less than 25,000 miles on it, riding on smooth tires? Can a case be made for a production orgy and short cycling of rental vehicles for a period of time as we had in the 1990s? For all the negativity attached to “push-marketing,” could this be an ideal time for it? The idea of manufacturing plants running at full capacity, paying overtime and adding shifts, and the trickle down through the supplier base and the financing community sounds pretty good right now. And the market could use a supply of low mile pre-owned units. Customers of Hertz, Avis, Dollar/Thrifty, etc., would be happy. And perhaps the auto industry could help touch off recovery like it has in the past.
David Ruggles has spent his career in every phase of the retail side of the auto business, new and used, sales and management, including consulting and training in both the U.S. & Japan. Ruggles has been a dealer for Mercedes-Benz, Chrysler, Dodge, GMC, Ford, Mazda, and Subaru, and has consulted for one of the world’s largest privately owned Toyota dealer groups located in Japan. He blogs at autosandeconomics.blogspot.com and writes regular columns for several publications.

Wednesday, August 3, 2011

Bob Lutz - "Car Guys versus Bean Counters" Book Review

"Car Guys vs Bean Counters"
The Battle for the Soul of American Business
By Bob Lutz
The automotive world has been waiting for this book for months. Lutz gave a preview to a group at a fleet conference I attended in Las Vegas last summer, where he received a Lifetime Achievement Award from the Automotive Fleet and Leasing Association (AFLA). His previous effort, “Guts: 8 Laws of Business from One of the Most Innovative Business Leaders of Our Time” made “best seller” lists.
Now 79, Lutz knows his auto industry history better than most. He has lived it in the most inner circles, having held executive positions for GM Europe, then, BMW where he coined the phrase, “BMW, The Ultimate Driving Machine.” Then worked with Lee Iacocca at Ford, followed him to Chrysler, where he lost out to Robert Eaton for the top job, perhaps the biggest mistake Iacocca ever made. After a stint as CEO of Exide Battery Corp., he rejoined General Motors. Who better to tell us the story of the struggle for authority and dominance in the various domestic auto companies, as well as the recent history of GM’s fall and rise?
According to Lutz, the GM he found when he returned in 2001 epitomized , “The tyranny of process over results.” He does so in true Lutz style as evidenced by his personal motto, “Often wrong but never in doubt.” Anecdote after anecdote kept me chuckling while I marveled at the man’s insight and ability to articulate. While Lutz comes across as confident, he also impresses with his candor and humility, free to admit a personal mistake or miscalculation. Then there is his notorious acerbic wit and occasional tendency to be blunt with comments like, “Global Warming is a total crock of sh*t,” made during a private lunch with reporters in 2008 but repeated over and over again by the press.
Lutz gets some things off his chest as he rails against government over reach, Toyota, CAFE, MBAs, and the “liberal media” one minute, then skewers Limbaugh, Beck, and the radical right wing the next. He spends a chapter on second guessing the tenures and decisions of others but does it in a humble way, pointing out that those people made sincere decisions based on their personal beliefs and information available at the time.
Lutz chronicles the history of GM from the days when iconic stylists like Harley Earl and Bill Mitchell ruled the roost. GM achieved market dominance by executing stylish cars that people lusted for because of their innovation and beauty. Post war Cadillacs, finned V8 Chevrolets, the Corvette, sixties era Toronados and Rivieras, and many other exhilarating vehicles resulted from when “Design” was dominant. This was replaced by the premise that, “You can’t manage what you can’t measure,” which led to bureaucratic process where no one tried to achieve anything other than to be perceived as not having made a mistake. Lutz calls it “analytics run amok,” preferring “art over science,” but seeing the need for both. “It’s the balance that has been out of whack.” He cites “penny wise and pound foolish” anecdotes one after another to make his points.
He singles out for particular scorn the “brand era” at GM, headed by Ron Zarella, brought over from Bosch and Lomb to be president of GM North America. Instead of designing desirable products first and then creating the underpinnings to make that design work, the first step in the new “bean counter” dominated GM was to create cost constrained underpinnings. The Design Department was then given the mission to “wrap the underpinnings in something that looks as good as it can under the circumstances.” This is the opposite of how things were done when “Design was Dominant” at GM. Lutz cites the ill fated Aztec, the “Quasimoto of Crossovers,” as an example. Over the years, GM had established “a stifling thicket of criteria: where the wheels had to placed relative to fenders, how the windshield should slope to permit easy viewing of traffic lights, how ash trays were to open and close, etc. etc.”
GM had purchased a Chrysler 300 to try to determine how Chrysler could develop such a vehicle, but GM couldn’t. The Design Department covered the car with 90 “Post It” notes, identifying areas where Chrysler had violated GM design criteria.
There was a time when GM paint was intended to be purposefully dull so as to not reveal flaws, in search for an optimum JD power score. There was no desire to excel or develop a “smash hit. The focus was on meeting “data points.” By following “process,” executives could avoid the accountability of failure as long as it was perceived they had followed the GM process.
Brand managers were recruited from companies like Procter and Gamble, and cars were developed and marketed by people who were deodorant, baby wipe, and toothpaste experts.
“The ebullient, dynamic, seductive volcano of creation had been transformed into a quiet mountain with a gently smoking hole at the top, spewing forth mediocrity upon mediocrity,” says Lutz.
The internal confusion at GM is exemplified by a conversation Lutz relates with an automotive supplier over lunch. At the time, Lutz was President of Chrysler. He asked the supplier who his favorite customer was. The answer came back, “GM!”
Why,” asked Lutz.
It seems the supplier was able to sell the same bearing under seven separate parts numbers, but in seven different boxes at wildly different prices. The purchasing departments rarely talked to each other. According to the supplier, doing business with GM was sure hard to keep straight, but it was mighty lucrative.
Lutz is careful to exclude GM trucks from excoriation, pointing out that the truck division produced success story after success story. Of course, everything changed when fuel prices suddenly increased, as they did in 2008. Not only did profitable truck sales suddenly cease, but the GMAC mortgage business, which had been subsidizing overall North American operations, started hemorrhaging cash at an astonishing rate.
Lutz tells his own version of the auto CEOs going to Washington D.C. on their private planes. He talks realistically about the firing of Rick Wagoner, and the role President Obama, Steve Rattner, and others played in the bailout. He discusses the fierce debate over whether or not the government should have taken a stock position in the new GM and about whether or not the UAW was favored in the deal. But you’ll have to read the book to find out what he said!
Lutz says, “In a sense, the decline, failure, and rebirth of General Motors is simply a metaphor for what is happening to business in the whole United States.”
According to noted automotive journalist, David E. Davis, Jr., “This book should be required reading for any young person who seeks a business degree." He also applies his advice equally to the current management of GM.

Wednesday, July 27, 2011

Japan's Twin Earthquakes and other disasters

Japan is well on its way to recovery from the March 11 earthquake that rocked the country’s northeastern region and generated a tsunami that swept clean swathes of the coast.  Automotive output is recovering; between them, Honda, Nissan and Toyota plan to hire over 5,000 temporary workers in an attempt to catch up, which feeds back to help the rest of the economy, as well as the Tohoku earthquake region where Toyota's newest plants are located. But a second and wholly man-made disaster now threatens the return to normalcy.
Despite the magnitude of the March temblor, Japan was well prepared. Few deaths stemmed from buildings collapsing, trains stopped automatically, and factories were relatively unscathed. As roads were reopened and utility service reestablished, the auto industry was ready to resume output. And all along most of the economy trundled on; despite the horrendous scope of damage, the impact of 25,000 deaths and the total destruction of a swathe of coastal land in a society of 127 million is limited. Rapid recovery seemed certain, as was the case after not merely the 1995 Great Hanshin earthquake which struck almost direct under Kobe, but even the 1923 Great Kanto earthquake, which destroyed the Tokyo metropolis.
The auto industry was a hiccup in that process. Today's cars are hi-tech products, and the supply chain is correspondingly complex. Let one example suffice. Making a semiconductor chip takes two months from start to finish, and the ceiling fell in ― literally ― at a plant where an invisible speck of dust results in a bad part. Doing basic repairs, getting the clean room clean again, and then debugging machines is a multi-month process. Given the uniqueness of the chips, symptomatic of their "hi tech" nature, it was just as difficult to transfer manufacturing to a different facility, despite excess capacity elsewhere. Japan is a big place, however, and a river of engineers poured in to help. As a result, even the Renesas' "fab" is back in production, albeit at reduced rates.
The global industry remains vulnerable to disruptions; factories are prone to be unique. One reason is that the industry has not settled upon standards–though a July 26 article noted a new effort in that direction. [See a Japanese-language article in Sankei on a METI-coordinated committee on the issue. It cites Toyota saying that by 2013 they might be able to start purchasing under joint standards, but such standards would not apply to more than 30% of semiconductors.] Part is that things are evolving too fast. But firms also view chips, specialty steels, paints, engine parts, and now batteries as strategic. And there are no institutions in place: the old standard-setter, the Society of Automotive Engineers, is a shadow of its former self. With little commonality, dual-sourcing is not an option, magnifying risk.
Hindsight is not foresight. It's impossible to take into account (much less insure against) every eventuality. While a few mayors along Japan's coast had insisted on unusually high flood walls ― maybe reflecting (possibly corrupt) ties to the construction industry rather than prescience ― disaster scenarios didn't anticipate the magnitude of the tsunami. That increased the human cost, even if relatively few plants were located on the coast: most were inland, where land was cheaper
One exception was power plants, which needed access to water for cooling. We all know about the destruction of a set of four of the six nuclear plants at Fukushima I. Less known is that the Onagawa nuclear plant, run by Tohoku Electric Power, was both directly hit by the earthquake and by a higher tsunami; after all, an idle but undamaged plant isn't "news". However, it was of a modern design, on higher ground, and better managed ― and shut down without problems. Even more telling, a second set of four reactors, the Fukushima II complex, were also effectively unscathed. Yet the Onagawa plant and the other well-run utilities with intrinsically safe nuclear plants are being tarred and feathered by TEPCO (Tokyo Electric Power). In the background not-in-my-backyard politics at the local and prefectural level made construction of new electric generation capacity of any sort a slow process. So there is little excess capacity, exacerbated by the division of the country into incompatible power grids. Every power plant has to be brought back online if the country is to avoid brownouts for the years to come.
Unfortunately, Japan now suffers from a second earthquake, entirely man-made. The disaster now unfolding reflects politics.
Why? Prime Minister Naoto Kan of the ruling Democratic Party of Japan (DPJ), facing a divided Diet (parliament), was too quick over the past year to offer compromise to the opposition Liberal Democratic Party (LDP). (Perhaps that reflects his background as a community activist and lawyer, where the key skill is being able to hammer out compromises where common interests are central.) In the process, he alienated many in his own DPJ, without ultimately gaining the cooperation from the LDP that he needed to pass legislation. Then, under pressure from all sides, Kan struck off on his own with a populist measure to keep all nuclear power plants closed once they shut down for maintenance under a routine 13-month cycle. Within a year, then, all will be closed and remain off-line. Most are of the more modern Onagawa design, but they may now never be permitted to resume operation despite providing 30% of Japan's electricity. The economic impact of this will be huge and last for years, even as the economic disruption from the Tohoku earthquake itself ends.
Still, it is useful to remember the basic competitiveness of the auto industry, with multiple suppliers and assemblers following a wide array of strategies. Contrast Nissan, relatively unaffected by the quake, with Toyota. Twenty-five years ago Nissan began moving its production inside Japan to Kyushu, 1,500 miles south of the quake's epicenter, while reducing capacity in the Tokyo region. [Nissan had also been planning to boost output and so had built up inventories of chips and other items with long lead times before the quake struck on March 11th, so there was an element of luck involved, too.]
Toyota's strategy was different. It had acquired Kanto Jidosha and Central Jidosha in the Tokyo area in the 1950s, which together with Toyota Auto Body account for 30% of the company’s Japan-based output. In the 1990s, rather than paring capacity, they added plants to the northeast of Tokyo ― right where the earthquake struck.
That extra capacity left Toyota vulnerable to a second earthquake: an appreciation of the yen, at ¥78.5 per dollar as I write this, over 50% stronger than the ¥121 level of July 2007. With the extra capacity, and a commitment to pay employees whether there was work or not, Toyota increased its dependence on exports; Nissan did not. Toyota also has a byzantine web of domestic subsidiaries, a structure as unwieldy as the General Motors of old, with internal politics to match. So domestic production was attractive not only to alleviate union pressure but to protect the turf of incumbent executives and middle managers.
Now the earthquake itself will have a fleeting impact. Japan is after all a large place, with 127 million people. Horrific as 25,000 deaths may be, that and accompanying losses to the capital stock are tiny relative to the size of the economy. Capital can be fixed, and the size of the economy makes that relatively straightforward: a cumulative 4,200 engineers and other skilled workers poured in from the rest of the domestic semiconductor industry to revive production at the Renesas plant. The same story applies to electric power lines, roads and bridges, and other infrastructure, including the Sendai airport that was but recently under water. Many farmers were unable to plant this year's rice crop, the fisheries industry is only partially functional, and tourism is dead -- and all are important to the rural Tohoku region. But Toyota's plants are running again, and those of their suppliers.
Yes, the Tohoku earthquake was a disaster, as is the ongoing rise of the yen. The impact of both is amplified by dysfunctional politics ― electoral and corporate. Nevertheless, the industry as a whole is remarkably robust: its size and the variety that comes from rivalry lessens the impact of even major disasters. Toyota may be hit, and its recovery will be far slower than most observers seem to believe. A few American consumers may be disappointed, Toyota's U.S. dealerships moreso. But the global industry will hardly notice.
Mike Smitka

Sunday, June 5, 2011

Taxpayers, The Auto Bailouts, and Politics

Last November, General Motors’ IPO set a record for money raised at 20.1 billion dollars. This is all money returned to the taxpayers’ Troubled Asset Relief Program (TARP). The success of the IPO was not only driven by new investors, but also by stockholders and lenders who had been “stiffed” in GM’s Chapter 11 bankruptcy of 2009. The company recently reported its highest quarterly profit in more than a decade, helped by demand for fuel-efficient cars and a big gain from selling its stake in its former auto parts business. The biggest U.S. automaker said Thursday that it earned $3.2 billion, or $1.77 per share, in the first quarter. It was a great start for the year considering the spike in U.S. gasoline prices, a trend that would have sunk the company just a few years ago when it relied on gas-guzzling pickups and SUVs for profits. Earnings will accelerate if U.S. auto sales continue to creep back up toward the 15-million to 17-million vehicle-per-year sales rates the U.S. industry last saw in 2007.
"GM is making a lot of money at ‘depression levels’ of sales. As the market improves it should make even more money." said Dave Cole, chairman emeritus of the Center for Automotive Research.
The U.S. Treasury will remain GM's largest shareholder for now. It will likely take several years to unload the entire stake to keep from diluting its stock price. Taxpayers still own about 33% of GM shares. The stock price will need to rise to about $48.00 for the U.S. government to break even on its follow-on stock sales. At $48 per share, GM would have a market value of more than $90 billion.
Chrysler Corporation paid back more than 7.5 billion in loans to the American and Canadian governments in May. Chrysler had until 2017 to repay the loans, so this was six years ahead of schedule. The company has now paid back most of the loan money that saved it from going under. The government loans were high interest loans, about which Fiat/Chrysler Sergio Marchionne recently opined. Instead of merely complaining about “loan shark rates,” the company did something about it. The high interest on the U.S. Government loans certainly induced Chrysler’s partner FIAT to borrow the money to pay off the bulk of Chrysler’s outstanding government loans. Chrysler raised just over 3 billion through a bond sale and took out 3 billion in lower interest loans to come up with the money to pay back the government loans. This will save more than $300 million a year, according to the company.
The automaker still owes taxpayers about $2 billion. Treasury could get most of that back by selling its remaining 8.6 percent stake in the company, which it was given in exchange for the loans. Chrysler’s IPO has yet to be scheduled but FIAT just announced it is increasing its stake in Chrysler to 51% from the current 46% in advance of the upcoming IPO. As Marchionne recently observed, “The longer we wait, the more it costs,” referring to FIAT’s intention to buy shares from the U.S. Treasury.”
Chrysler’s recent earnings have also been strong, despite a market impacted by high fuel prices and a weak, but recovering, economy. Both companies stand to do extremely well as the economy improves and the SAAR rises to recent historical levels.
Both companies have announced initiatives to increase production and rehire thousands of workers. Chrysler alone has added more than 8,000 jobs since its bankruptcy.
In the meantime, Ford continues to do well in the still recovering economy despite having to bear the weight of interest on debt it accumulated to ride out the economic storm without having to seek taxpayer involvement. Ford has benefited from union concessions it received to maintain parity with its competitors.
The auto industry bailout, financed through the Bush Administration’s TARP program, spared the GM, Chrysler, AND Ford from liquidation and saved hundreds of thousands of manufacturing jobs at those companies and its suppliers.
To add perspective, had either company been forced into liquidation, the cost dropped on the taxpayers in the form of the Federal Pension Benefit Guarantee Fund would have been at least $38 billion. This in addition to the damage that would have been done to the North American industrial base, including military procurement at a time of two wars.
While Americans have been known to pile on “losers,” failures, and those who make mistakes, they love “redemption.” While there are those who refuse to buy a GM or Chrysler vehicle OR buy their stock because they were bailed out by the government, the companies’ strong sales and profit results indicate that, on balance, they are achieving a large measure redemption. The popularity of Chrysler’s “Made in Detroit” advertising campaign is further evidence.
In the meantime, the 2012 election campaign is getting underway and yes, it looks like the bailout of the auto industry could end up being one of many points of debate. One can expect Democrats to replay videos of Republicans who opposed the bailouts ad nausea. Already an ad paid for by the Democratic National Committee recaps positions taken by Mitt Romney, Newt Gingrich, and Tim Pawlenty.
Romney takes a significant hit in the ad. The former Massachusetts governor, whose father was governor of Michigan as well as the top executive at American Motors is being reminded of the hard-lined position he took in a 2008 New York Times Op Ed, “Let Detroit Go Bankrupt.” Yet Romney and others continue to use opposition to the bailouts as a campaign point, advocating a free-market system free of bailouts and subsidies. They maintain that even now it still looks like the bailout came at quite a cost to taxpayers, despite substantial evidence to the contrary. They maintain that allowing the automakers to go into liquidation wouldn’t have been such a terrible thing, which is easy to say since it didn’t happen.

Democratic candidates will point to the relative success of TARP and the auto company bailouts and paint a picture of what would have happened had TARP not been enacted and either company had liquidated.

As politics heats up leading up to the 2012 national elections, expect debate over the auto bailouts to play a major role in determining political winners and losers.

David Ruggles has spent his working life in every phase of the retail side of the auto business, new and used, sales and management, including consulting and training in both the U.S. & Japan. Ruggles has been a dealer for Mercedes-Benz, Chrysler, Dodge, GMC, Ford, Mazda, and Subaru, and has consulted for one of the world’s largest privately owned Toyota dealer groups located in Japan. He blogs at autosandeconomics.blogspot.com and writes regular columns for several publications.

Wednesday, May 4, 2011

Contango

And other issues not commonly understood by consumers about the world oil market
The higher the price of gas at the pump, the more sensitive consumers are to allegations of oil market price manipulation. Most consumers are unaware exactly how any manipulation takes place, but they can't square the doubling of the price of a gallon of gas when the price of a barrel oil doesn't double, so they are suspicious there is a culprit to be blamed. Oil companies become the bad guys as they report high profits.
Well there IS oil market manipulation by the most major of oil traders. AND it isn't even illegal. But it takes tremendous amounts of capital to manipulate the world market price of oil. For a variety of reasons, the best known energy trader manipulating the world market price of oil is Koch Energy, probably because of the Koch brothers high profile participation in the political process.
So what is "contango?" Contango is the strategy of purchasing large stocks of oil and storing it in offshore supertankers and giant containers, creating a shortage or exacerbating a real or perceived shortage in the market. The trading company then it sits on those supplies until oil prices rise.
Ever wonder how gas prices can be $4.50 per gallon in say July 2008, and then drop to $1.90 when President Obama was inaugurated In January 2009 six months later? Crude oil prices dropped from more than US$145 per barrel in July 2008 to less than US$35 per barrel in December 2008.
When the contango hoarders turn their stocks of oil loose on the market at the peak price, it tends to flood the market with oil, especially when consumers have cut back on consumption due to the high price. At the same time all producers pump and transport like crazy to take advantage of the high price, including those in the oil patch. The end result is a glut and cheap fuel at the pump. And consumers end up with fuel price volatility. U.S. consumers tend to think they are entitled to the "glut" fuel prices, rather than the highest price or even an intermediate price.
For those who recall, the Bass Brothers' play on silver in 1977 and 1978 was a form of contango.


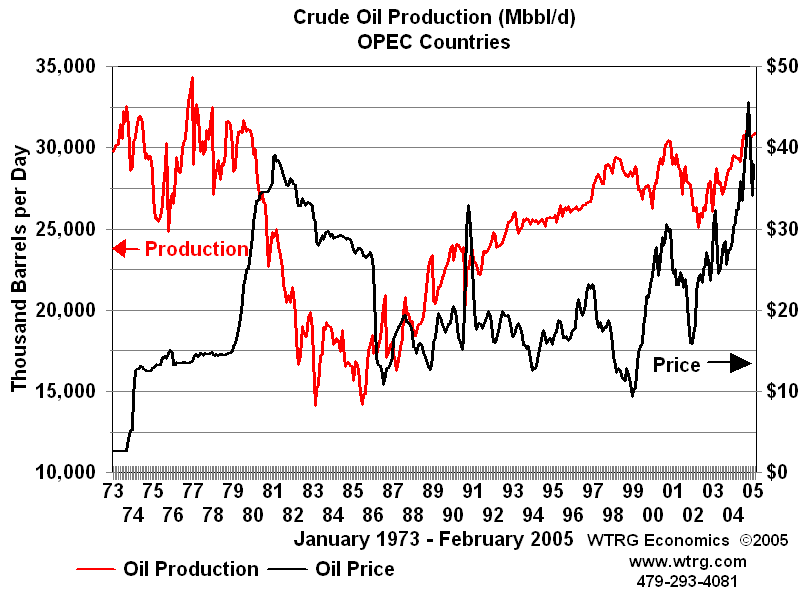
But there is another example of "hoarding" on a much larger scale. OPEC has been hoarding oil for 35 years. In 2011 there are more members of OPEC than in 1973 and world wide consumption has accelerated. Yet, OPEC doesn't produce any more oil today than they did in 1973. OPEC is not in the business of just selling volumes of their finite resource, as much as maximizing the price they get for each barrel. The U.S. produces about a third of its oil domestically. We get another third from Mexico and Canada. The final third comes from OPEC. What is not clear to most Americans is that if we double our domestic production, and eliminate the OPEC purchases, we still have not freed ourselves from the world market price of oil. Why? Because Americans do not own the oil produced here, the oil company that makes the investment to find it and produce it owns the oil. The chances of an oil company selling their oil to the U.S. consumers at less than the world market price is slim and none. Yet, I don't hear a lot of talk about nationalizing the oil companies.
Further, when we increase production, OPEC cuts theirs back a like amount to maintain the supply/demand balance. The graph at the following link shows the production of OPEC over the decades: (graph link)
More domestic production WOULD improve our balance of payments situation, but it would quickly eat up our meager oil reserves. The U.S. maximized domestic oil production in 1970 and uses 25% of the world's production while owning less than 5% of known reserves. We ramp up production, OPEC cuts theirs back, and we use up our reserves without saving a dime. So much for “Drill Baby Drill.”
Off shore and ANWR reserves seem like a lot of oil until weighed against U.S. consumption. OPEC sits on 70 - 80 percent of the world's known reserves, to put things in perspective.
There are those who think we are better off to use up others' reserves and keep ours for a rainy day. The Bakken Formation oil shale reserves in the Dakota and Montana ARE huge! Bakken currently produces about 500 million barrels of oil per day.
BUT oil shale development requires large expenditures of water and energy, produces air pollution and carbon emissions and leaves toxic byproducts that endangers the environment, especially the water table. For example, a fully developed Bakken formation could leave the entire Southwestern U. S. with a huge water problem. In addition, the high cost to produce from oil shale in Bakken is only viable when the world price of oil is between $80. and $100. per barrel. Major investment in Bakken on oil shale development has been tentative as investors are afraid OPEC would open their spigots to drive down the price of oil, throwing them into bankruptcy.
While there isn't much we can do about hoarding by OPEC, there have been initiatives to tighten regulations on commodity and derivatives trading. Lobbying against this regulation has been fierce. In fact, the same Commodities and Futures Trading Commission (CFTC) is the same government agency that tried to regulate credit default swaps and collateralized debt obligations on Wall Street. Larry Summers, Alan Greenspan, Robert Rubin and others blocked the efforts to regulate commodities and derivatives by firing the chairman of the CFTC, Brooksley Born, and replacing her with Wendy Gramm. Yes, this is the same Wendy Gramm that was on the board of directors of ENRON when its energy trading speculation and suspect accounting wiped out millions of investors AFTER she had blocked regulation that would have prevented it from happening.
For now, large energy traders continue to benefit from the lack of regulation while U.S. consumers suffer to a greater extent than necessary.
Over his 40 year career David Ruggles has been in every phase of the retail automobile business and has consulted with and done training for hundreds of auto dealers in the U.S. and Japan. He conducted a yearly seminar for one of the world's largest privately owned Toyota dealer groups for eighteen years, and has himself been a dealer for Chrysler, GMC, Mercedes Benz, Ford, Mazda, and Subaru. Author of the Ruggles Report, and a regular contributor to the National Bureau of Asian Research, he blogs at autosandeconomics.com and writes regular columns for several trade publications and The Daily Post online newspaper. He is a member of the International Motor Press Association.

Thursday, April 28, 2011

Cars and Roads

I'm now teaching my annual 4-week-long Spring Term course on the auto industry at Washington and Lee University, Economics 244, which will include one week in Detroit. Ironically, it has left me too busy to blog on the auto industry. So this will be short.
It's very easy in our narrow focus on the manufacturing and distribution of cars to overlook the revolutionary impact that comes from greater mobility. A note on a World Bank project in Laos highlights that. (Here's the link.)
The blog by Victoria Minoian traces the changes the follow from building a road that allows motorized access. Rural farmers can now grow vegetables for town and city markets, and not merely for own consumption. That is, they can earn a cash income. Doctors can access a village otherwise cut off on frequent occasions by high water. Children can get to school &endash; though perhaps by bicycle rather than motorized vehicle. There's little point in building good roads without motorized vehicles; but without roads, vehicles are also of little use. Of course the location of the village from which these examples were drawn reflects that constraint: it was alongside a river (the Mekong, not just a little river). The village wasn't necessary poor by local standards. But while boats and rivers make a difference, roads and motor vehicles make a bigger one.
Mike Smitka